In December 2020, after DHA Lahore prices jumped in the months after the first COVID lockdown, Husnain wrote his original version of this article: the smart money buys when the market goes quiet and sells when everyone is chasing the same plot. Six years on, the idea still holds. What has changed is the market, the taxes and the interest rate, so this is the 2026 version, written for Lahore buyers and overseas Pakistanis.
What does “buy when others are fearful” mean in property?
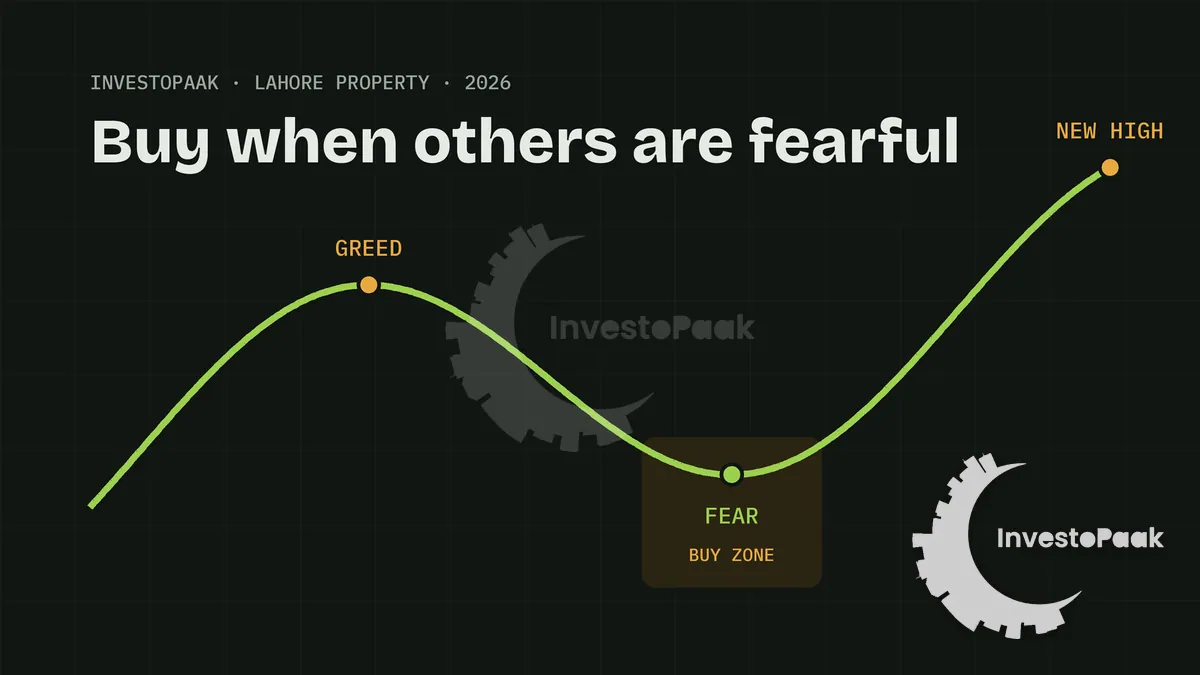
It means buying good property when sellers are under pressure and buyers are waiting, and slowing down when everyone is rushing in. Warren Buffett's line is about stocks, but property follows the same psychology: when confidence drops, sellers who need cash accept lower offers, and buyers wait for a “signal” that never arrives clearly. When confidence returns, the same buyers rush in at higher prices.
Nobody can call the exact top or bottom. The goal is simpler: avoid buying in a frenzy, and be ready with cash and homework when a good block goes quiet.
Is the Lahore property market fearful or greedy in late 2026?
Neither extreme. Lahore is rising steadily, and that is when overpaying is easiest. Three numbers tell the story:
- Prices are rising. Zameen's price index put the average Lake City residential plot at about PKR 1.97 crore in May 2026, roughly 21% higher than a year earlier.
- Money is not cheap. The State Bank held its policy rate at 11.5% in September 2026, with inflation around 10–11%. Property has to beat that to make you richer in real terms.
- Buying and selling got cheaper for filers. From 1 July 2026 the Finance Act 2026 cut the buyer's and seller's advance taxes and removed the Section 7E tax on holding property. Non-filers still pay several times more.
| Tax | Until 30 June 2026 | From 1 July 2026 |
|---|---|---|
| Buyer's advance tax (236K) | 1.5% to 2.5% of value | 1.25% flat |
| Seller's advance tax (236C) | 4.5% to 5.5% of value | 2.75% flat |
| Holding tax on property over Rs 25 million (7E) | About 1% of value a year | Removed |
Older rates varied by property value; see Mettis Global's Finance Act commentary. Stamp duty and the society's transfer fee are extra. Lower trading costs and steady price growth mean more people are buying, which is exactly when this rule matters most.
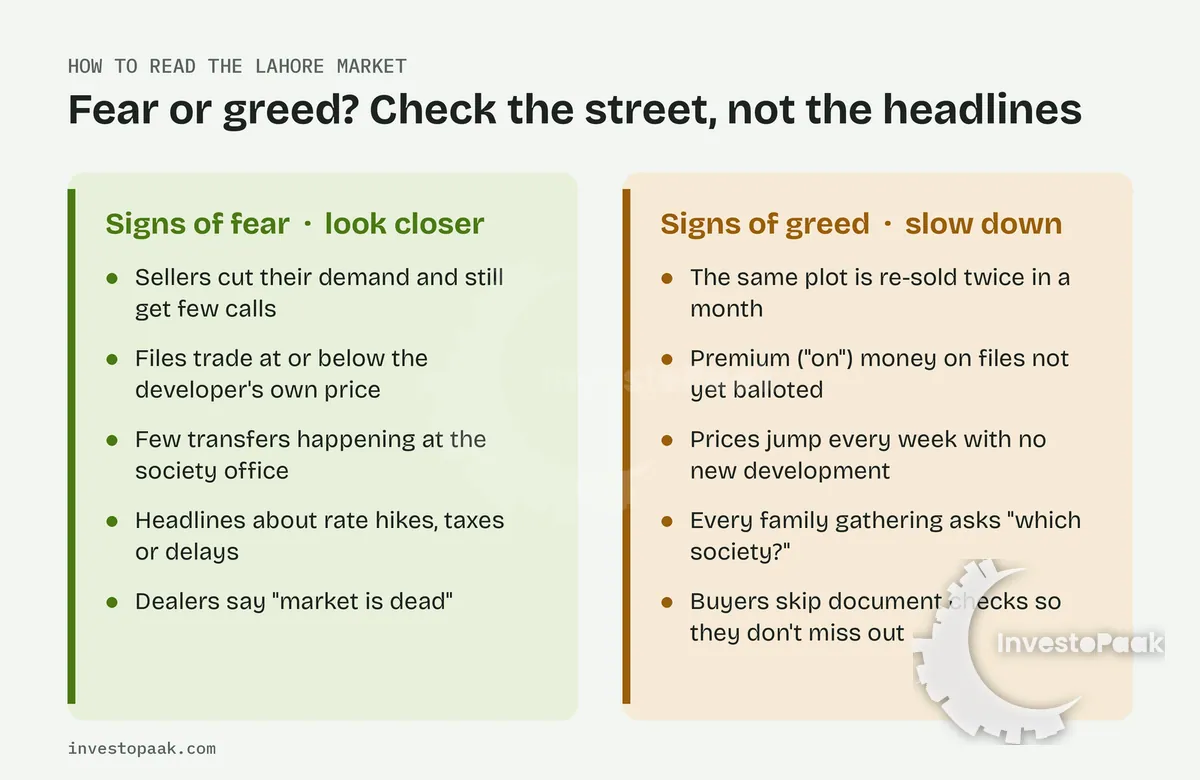
Where do you find fear when the whole market is rising?
Block by block. Even when the city is up, fear shows up in pockets: a block where development is behind schedule, a new phase whose ballot keeps getting delayed, or a seller who must close this month because of a family need. That is where fair deals are. The headline average hides them.
In Lake City, for example, blocks with roads, electricity and houses already built trade very differently from blocks that are still open land. A quiet block is not automatically a bargain. It is a reason to visit, check the development on the ground, and compare transfer prices, not asking prices.
How do you buy a dip without getting burnt?
- Verify before you get excited. Check the file or registry, NOC and transfer history first, using our verification checklist. Cheap is often cheap for a reason.
- Pay for development, not promises. Prefer blocks where roads, utilities and houses already exist.
- Keep holding power. Buy with money you won't need for 3–5 years. Never borrow at 11.5%+ to chase a dip.
- Count every cost. Add 236K, stamp duty, transfer fee and commission to the price before you compare. For installment files, run the numbers in the payment plan calculator.
- Decide your exit on day one. Write down the price at which you will sell, and stick to it when the next rush comes.
To compare real asking prices, see the plots and houses on our current listings, each with its price per marla.
When should you sell property in Lahore?
Sell into greed, not fear. When the same plot is re-sold twice in a month, when “on” money appears on files that haven't been balloted, and when prices move faster than development, it is time to take some profit, not to add more.
Want to know if a block is quiet or overheated right now? Husnain replies on WhatsApp.
Talk to Husnain on WhatsAppThis article is general market information, not personal investment advice. Prices and tax rates change; confirm current figures before you buy or sell.